
Start with the definition
I would copy the relevant relationship wording into your comparison notes. Keep your everyday description of your partnership separate from the terms the policy actually uses.
I would choose the best travel insurance for couples by comparing companion definitions, household eligibility, covered reasons, documentation and each traveler's insured costs. A couple label does not establish protection. The better fit addresses both partners' relationship, travel arrangements and specific reasons for canceling.
I approach the best travel insurance for couples as a policy-fit decision, not a provider ranking. For Long Island travelers, the best travel insurance for couples should fit your relationship, household arrangements and cancellation concerns.
When comparing the best travel insurance for couples, I separate traveler eligibility from a payable claim. I am Heather Hamann; my specialties are cruise planning, custom vacations and group travel. These five provisions help me evaluate whether a proposal fits both partners.
I would copy the relevant relationship wording into your comparison notes. Keep your everyday description of your partnership separate from the terms the policy actually uses.
I would record separate addresses, reservations and arrival dates where applicable. Those details make it possible to test the wording against the trip you are actually taking.
I would describe the event that worries you, not simply write that one partner cannot go. That gives you a specific event to compare with the covered-reason provision.
I would organize booking records before departure and obtain the insurer's documentation instructions. A tidy itinerary helps explain your arrangements, but it does not prove that a cancellation event is covered.
I would list each traveler's costs alongside shared purchases. If one person pays for both, preserve that fact rather than assume payment method determines how the insurer allocates coverage.
I begin with the definitions used by the benefit you need: spouse, domestic partner, family member or traveling companion. I read each relevant definition rather than treating these labels as interchangeable.
The question is whether the provision recognizes your relationship or shared arrangements, not whether the marketing sounds welcoming to couples. I then trace the definition into the cancellation benefit; its appearance elsewhere does not establish how that benefit works.
Say you are unmarried partners planning a romantic getaway and want to cancel together if either person cannot travel. I would first identify the wording addressing the affected person, then the provision permitting the other traveler to cancel.
I would favor clear answers to both questions over a summary that merely mentions couples. Where wording is ambiguous, a written explanation tied to the exact provision helps distinguish a suitable proposal from one that still leaves your question unanswered.
My comparison would also record the policy version and applicable residence information. That keeps any explanation attached to the document under consideration, rather than a similarly named product with potentially different terms.
I describe addresses and reservations exactly as they are. Living together, sharing a room and using one booking are different facts; none substitutes for another when testing eligibility.
For partners living separately, I examine any residence requirement attached to the relevant definition or benefit. I compare it with both travelers' circumstances, rather than assuming that being a couple settles the question.
Shared travel need not mean identical itineraries. Partners might arrive on separate flights or return on different dates. I would test how the wording describes their participation in the shared trip.
Say you book flights independently but share a Caribbean all-inclusive vacation. I would place both flight itineraries beside the accommodation reservation and evaluate the companion wording against that complete picture.
In that example, I would distinguish the shared stay from any days spent traveling alone. A proposal that clearly addresses the shared reservation but leaves the separate travel days unclear does not yet answer the whole itinerary question.
I compare joint and separate proposals without assuming either wins. A joint proposal may fit both travelers; separate proposals may better reflect individual arrangements. Separate policies add comparison work: I would trace the same cancellation concern through both documents, since matching product names do not establish matching protection for each person's circumstances.
Illustration of separate household routes and transport tickets converging on a shared stay with paired suitcases, with onward paths to a small house and trees.
I separate who is recognized from what happened. Relationship eligibility answers the first question; covered-reason wording answers the second. Both matter when one partner's problem changes the other's plans.
My starting example is specific: one partner becomes ill before departure, and the other wants to stay home with them. I evaluate each person's position separately because the same event need not produce the same claim outcome.
For the ill traveler, I examine the illness provision and its conditions. For the other, I trace cancellation through the applicable relationship or companion wording. This reveals whether the proposal addresses both concerns or only one.
I would summarize the result for each traveler as the relevant definition, covered reason and conditions still to satisfy. If I cannot connect those pieces for the healthy partner, I would not describe the illness example as protection for both.
I compare these paths before price. A cheaper proposal that misses your main concern is a poor fit, regardless of unrelated benefits.
My cruise insurance reading provides broader context on cancellation, interruption and other protections. I also distinguish canceling before departure from leaving after travel begins. For an escorted tour or river cruise, I would test both scenarios against their respective provisions, not assume that an answer about cancellation also establishes protection for an early return.
I separate relationship information, travel records and evidence of the cancellation event. Each group answers a different question; a shared reservation alone does not establish a covered reason.
I obtain the proposed policy's claim instructions rather than rely on a generic document list. The insurer identifies requirements for the relevant benefit. I would not promise that any particular certificate or booking confirmation is sufficient.
For separate bookings, I preserve records connecting the arrangements, such as shared accommodation alongside individual transport itineraries. I keep original booking details intact, plus cancellation confirmations and refund records showing what financial loss remains.
If your European vacation includes independently booked components, organizing by traveler and supplier makes the timeline easier to follow. Trip records explain the arrangements; event evidence explains why plans changed. Neither replaces the policy's eligibility requirements.
I would use an approved submission method for sensitive relationship or medical documents and send only what the insurer requests. The categories below help me organize records, not predict payment or replace claim instructions. Each document should answer an identifiable question in the review.
| Records | Help explain | Do not establish |
|---|---|---|
| Relationship information | Partners' connection | Eligibility under every definition |
| Travel confirmations | Shared arrangements | A covered event |
| Event documentation | Reason plans changed | Partner recognition |
| Payments and refunds | Remaining costs | Claim payment amount |
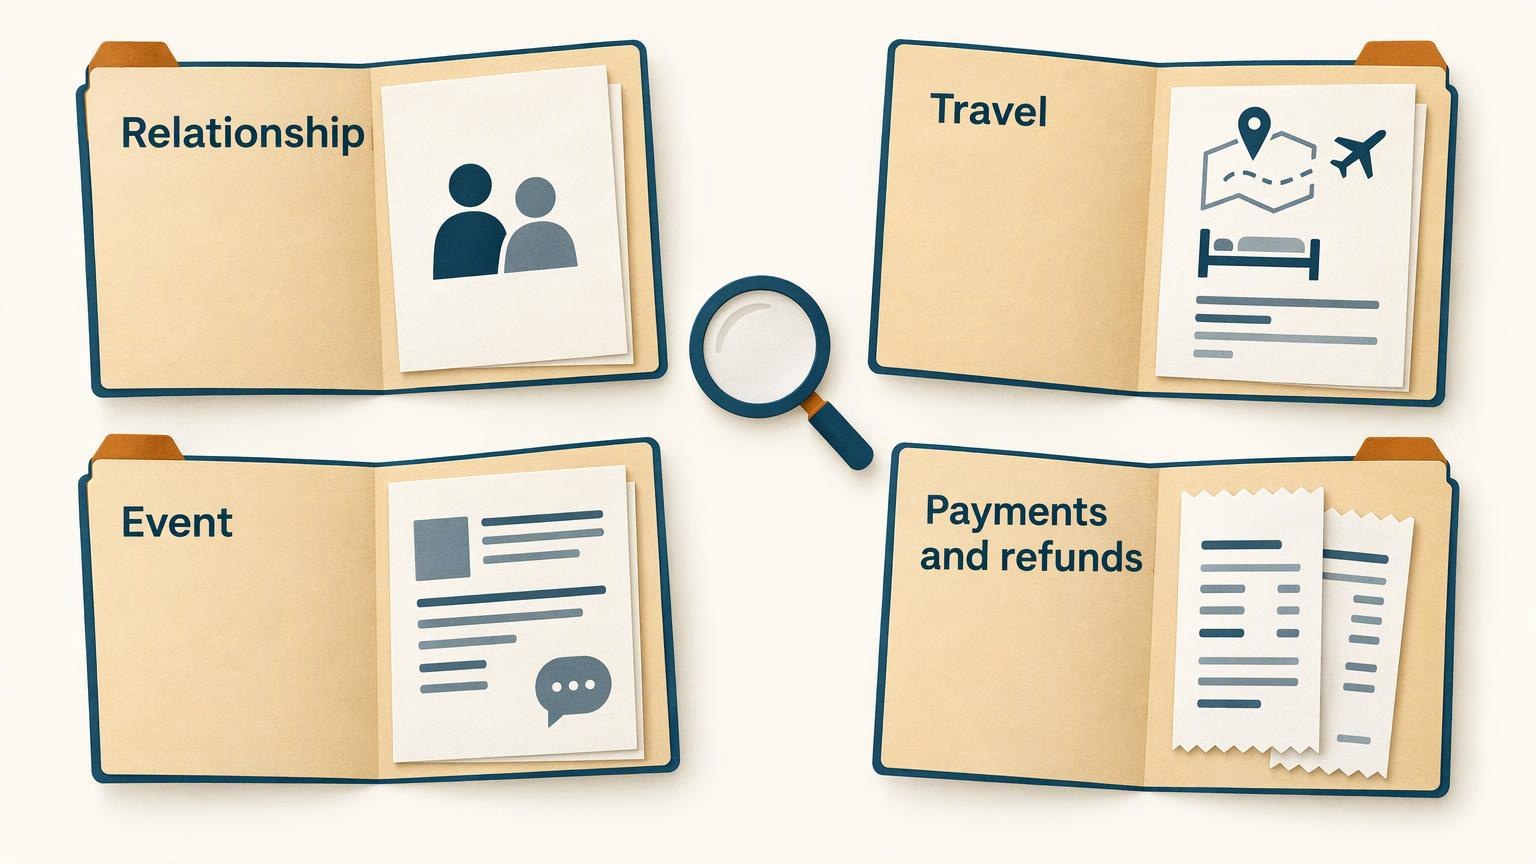
Illustration of four labeled record folders in a two-by-two layout, with paired-person, travel, document and receipt symbols surrounding a magnifying glass.
I create a cost record for each traveler before comparing quotes. I list individual purchases and shared charges, identifying prepaid amounts, cancellation terms and available supplier refunds or credits.
Say one partner pays for the shared room while the other buys both transport reservations. I preserve payment records and examine the proposed policy's allocation method. The payer and the insured traveler are not necessarily interchangeable.
I reconcile that method with your records before entering a combined total. An equal split may be convenient, but convenience does not establish how the wording allocates expenses.
I compare each person's benefits and limits with their costs and other needs. Cancellation protection and medical benefits serve different purposes; the cancellation amount alone cannot explain the whole proposal's value.
For couples joining a family or group cruise vacation, I keep individual exposure separate from the wider party's purchases.
I would request a current quote using matching traveler details, dates, insured amounts and benefit selections. Ask the insurer which inputs drive the premium, then weigh price differences against inclusions, limits and wording. A shared purchase does not establish a shared claim outcome.
Share the destination, dates and travel style you have in mind. A Superior Travel advisor will help turn the possibilities into one clear, personal plan.