
Start with your biggest loss
I would identify whether your main concern is replacing clubs or losing prepaid travel spending. That priority tells you which policy provisions deserve the closest comparison.
I would choose the best travel insurance by matching written terms to your clubs, prepaid bookings and activities. Compare eligibility, limits and exclusions against your priorities. A baggage benefit does not establish club protection, and nonrefundable green fees do not automatically qualify for reimbursement.
I compare the best travel insurance by identifying what you could lose on a golf trip. For Long Island travelers seeking the best travel insurance, I separate clubs, prepaid rounds and other vacation costs.
My approach to the best travel insurance starts with policy wording, not a golf label. I am Blake Rehfield at Superior Travel Consultants, an advisor-led agency on Long Island.
I would identify whether your main concern is replacing clubs or losing prepaid travel spending. That priority tells you which policy provisions deserve the closest comparison.
I would list equipment individually rather than record only the bag's total value. Ask how the proposed policy treats a set, an individual club and accessories.
I would record green fees and tee-time deposits apart from flights and accommodation. That lets you ask whether each purchase is an eligible insured cost.
I would distinguish a recreational round from a competition when presenting your plans. A general mention of golf is less useful than an accurate description of participation.
I would save the policy version, schedule and written clarification together. Retain booking receipts as well, so the arrangements and terms you accepted remain easy to find.
I would obtain the full proposed policy wording and benefit schedule before comparing quotes. A summary helps locate benefits but cannot establish whether clubs or separately prepaid rounds qualify.
My first pass separates belongings, purchases and activities. Each category raises a different question: what property is eligible, which costs can be insured, and whether participation affects a benefit.
I would then identify the loss you most want addressed. Replacing a damaged club and recovering an unused round are different objectives; an answer about one cannot settle the other. This gives the comparison a priority rather than treating every benefit heading as equally important.
For matching quotes, I would keep travelers, itinerary and declared costs consistent. A lower premium could otherwise reflect a different proposal, not a better fit. I would leave open golf questions open until the insurer identifies the applicable provision, rather than treating silence as permission.
I would start with eligibility, not the headline baggage limit. Ask whether owned clubs, rented clubs, the travel bag and accessories meet the policy's definitions, and which loss or damage events qualify.
Next, I would compare equipment values with aggregate limits, per-item limits and deductibles. Ask whether a set counts as one item or several, and whether an equipment restriction overrides broader baggage terms. A generous total limit may still leave an individual club inadequately protected.
I would examine valuation too: repair cost, replacement cost or an amount adjusted for age and condition. The limit alone cannot show how closely an eligible payment would match your replacement expense.
My review would distinguish transport damage from damage while playing. I would examine checked baggage, vehicle storage, unattended property and packaging requirements without assuming any circumstance is covered or excluded.
Finally, I would review delayed clubs and temporary rentals separately. Replacement protection does not establish rental reimbursement while your bag catches up. Before relying on rentals, I would obtain the relevant terms, including eligible expenses, limits, required receipts, incident reports and reporting deadlines for a claim.
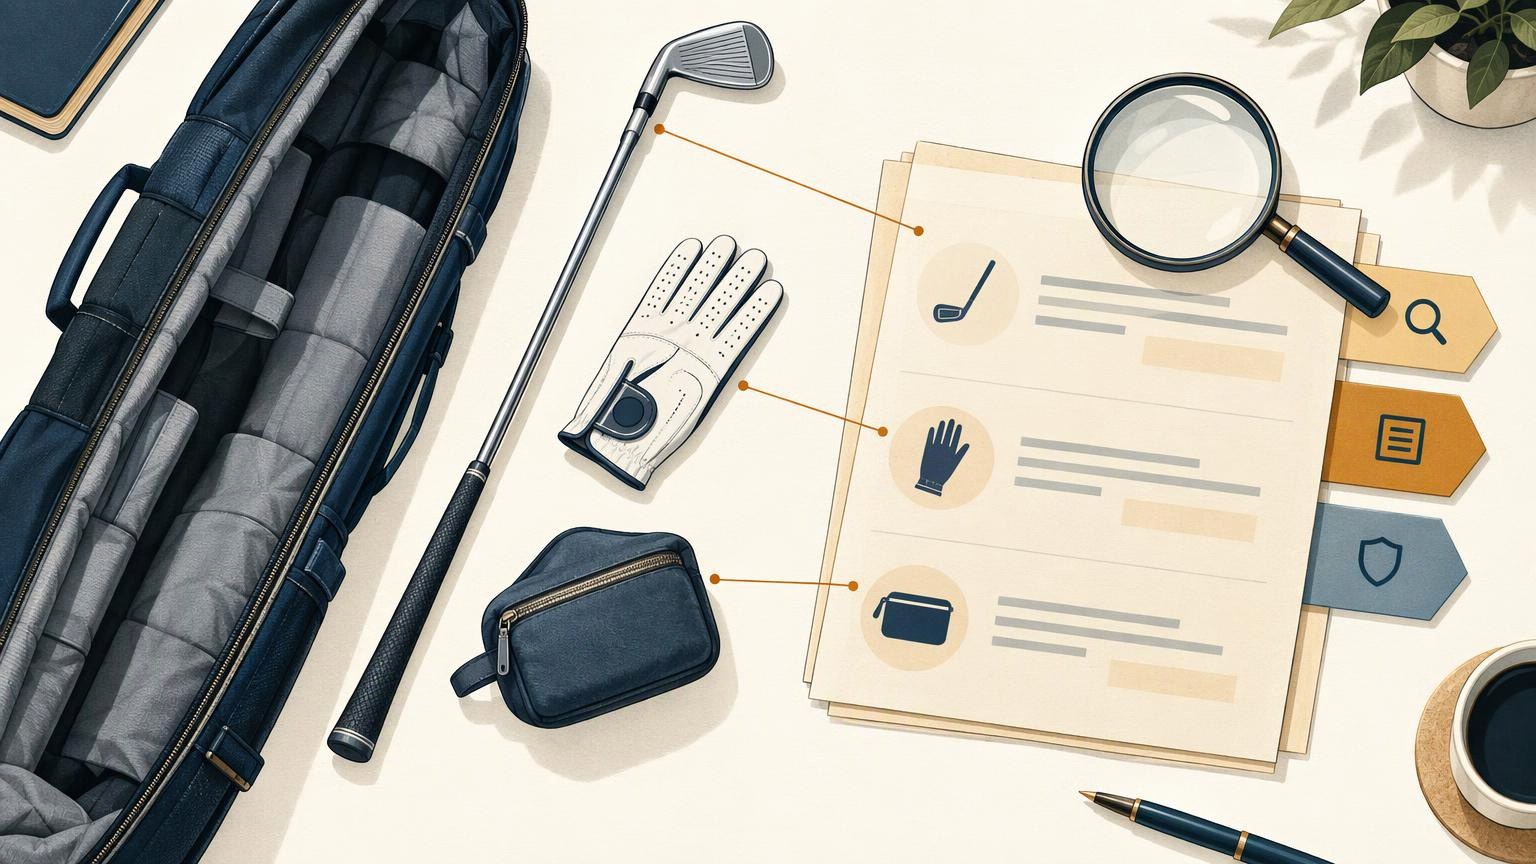
Illustration of a desk with separated golf equipment linked to matching entries on papers, alongside a magnifying glass and three pictogram tabs.
I would separate the booking's refund rules from insurance cancellation terms. A nonrefundable green fee establishes a potential loss, not reimbursement eligibility.
My comparison asks whether the purchase is an eligible insured trip cost and whether the cancellation reason meets policy conditions. Both must be addressed before relying on protection.
I would list prepaid rounds, tee-time deposits and package components with receipts and refund conditions. For golf added to an all-inclusive vacation or a European itinerary, I would distinguish included arrangements from independent purchases. That separation makes it easier to identify which costs remain at risk after supplier refunds.
I would test canceling before departure, leaving early and missing a round while continuing the vacation separately. A cancellation provision cannot answer an interruption or missed-activity question; I would locate the terms relevant to each outcome.
If weather is your concern, I would examine course refunds alongside the policy's conditions. A spoiled round does not establish an insured event. For golf alongside a sailing, I would use the cruise-insurance guide to frame sailing-related questions, not as evidence that green fees are covered by your proposed policy.
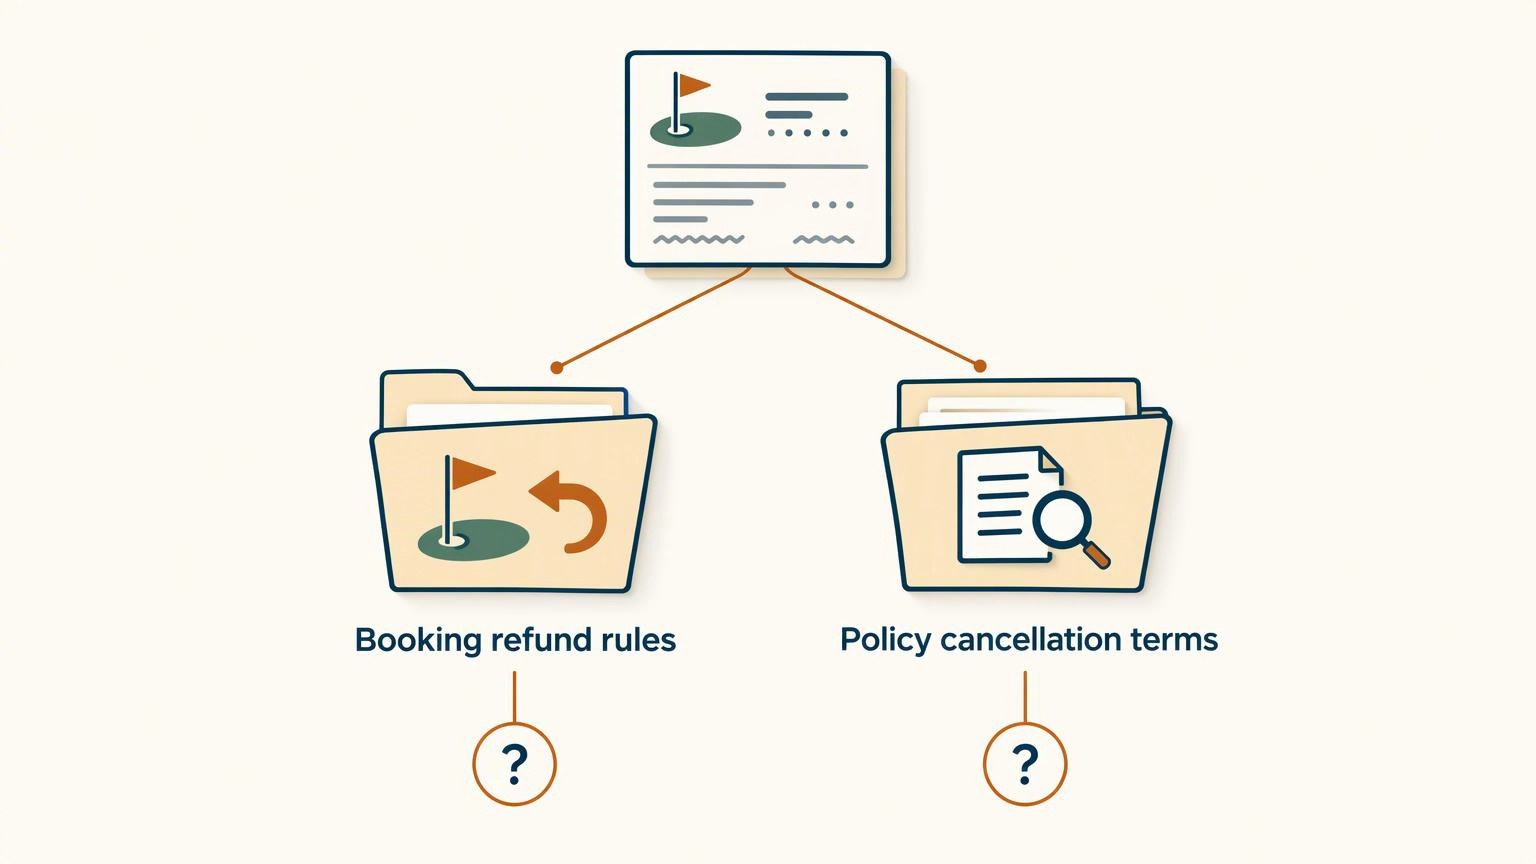
Illustration of a golf booking slip branching to separate refund-rule and policy-term folders, with a flag and return arrow on the left and a document and magnifying glass on the right.
I would review activity eligibility independently of equipment protection. Coverage for clubs cannot establish whether an injury during your planned play qualifies for medical benefits.
I would describe recreational rounds, lessons or competition accurately, then ask the insurer to identify relevant definitions and exclusions. I would name other planned activities too, rather than assume a golf discussion settles the itinerary.
For medical benefits, I would examine eligibility, limits, deductibles and requirements involving existing health conditions. I would also review emergency assistance, evacuation and authorization requirements before relying on particular arrangements or expenses. An activity being eligible is only one part of evaluating the medical benefit.
For couples or families, I would identify who plays, owns equipment and has prepaid costs. Sharing a vacation does not establish whose property or expenses qualify, so I would match each concern to the relevant traveler.
In my family and group travel planning discussion, I would separate individual arrangements and examine how the policy defines a traveling companion. I would also review cancellation affecting only part of the group, especially when one golfer cannot go but others still intend to travel.
Suppose you are bringing your clubs and have separately prepaid a round. Damaged equipment is your main concern, but you also want to understand the green-fee consequences if you cannot travel.
I would first help organize the itinerary and purchases. You would supply equipment values, receipts and proposed policy documents; the insurer would clarify applicable coverage terms.
I would compare equipment provisions first. A cheaper proposal expressly excluding your clubs would fail your main objective despite a generous baggage limit. For a proposal including them, I would examine limits, deductibles and valuation to judge how much replacement expense could remain yours.
I would then evaluate the prepaid round independently. Even if it qualifies as an insured cost, the cancellation reason and other conditions still matter. Equipment eligibility cannot resolve that question. If neither proposal addresses your priority, I would not select one merely because its premium is lower.
A better equipment fit may cost more and still leave losses to absorb. My specialties are custom vacations, cruise planning and group travel. I can connect questions to your itinerary; insurer wording remains the coverage basis.
| Priority | Terms to compare | Decision consequence |
|---|---|---|
| Clubs | Eligibility, limits, deductible, valuation | Baggage limits cannot override an equipment exclusion. |
| Prepaid green fees | Eligible costs, cancellation reasons, refunds | Nonrefundability alone does not establish coverage. |
| Temporary rentals | Delay eligibility, rental terms, limits | Replacement protection does not establish rental reimbursement. |
| Medical care | Activity exclusions, medical limits and conditions | Club coverage does not establish medical eligibility. |
| Priority | Terms to compare | Decision reminder |
|---|---|---|
| Clubs | Eligibility, limits, deductible, valuation | Baggage limits cannot override exclusions. |
| Prepaid green fees | Eligible costs, cancellation reasons | Nonrefundable does not mean covered. |
| Temporary rentals | Delay eligibility, rental terms, limits | Check rental reimbursement separately. |
| Medical care | Activity exclusions, limits, conditions | Club cover does not prove medical cover. |
Share the destination, dates and travel style you have in mind. A Superior Travel advisor will help turn the possibilities into one clear, personal plan.